For buyers, the list price is only part of the affordability equation. A home may be priced within a buyer’s target range, but the monthly payment can ultimately determine whether the property feels comfortable enough to move forward.
That’s why seller incentives are becoming an increasingly important part of the conversation. Instead of focusing only on a price reduction, sellers can sometimes use financing incentives to address one of the biggest concerns buyers have: the cost of their monthly mortgage payment.
That is the idea behind a potential seller-paid 2-1 buydown at 12316 Coolmeadow Ln in Dallas.
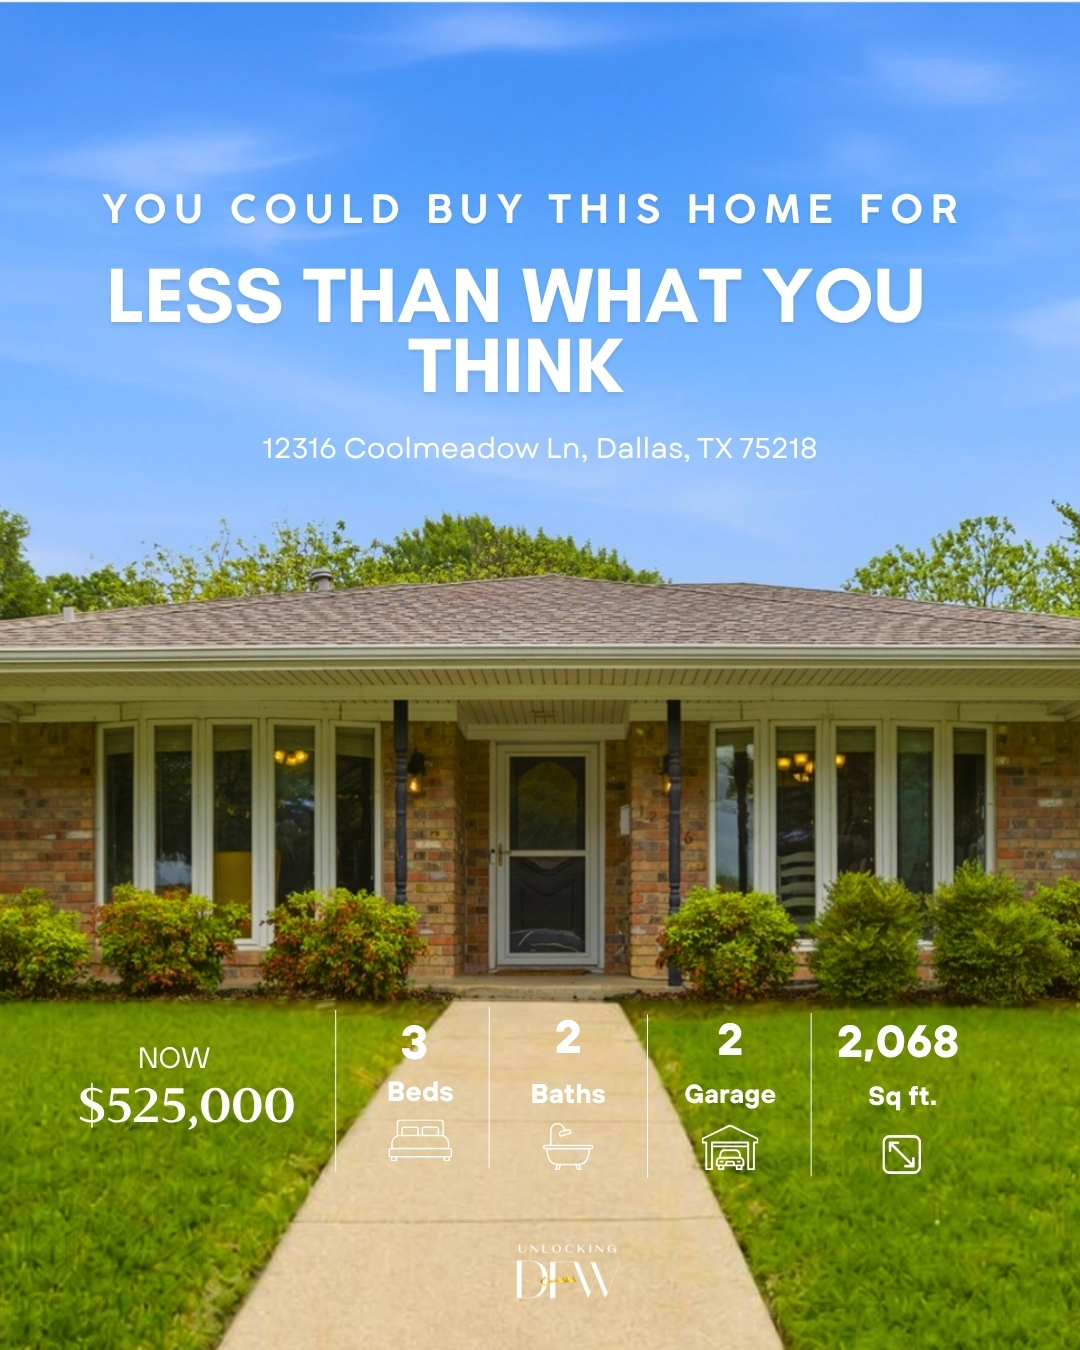
The home is currently listed at $525,000. After more than 25 showings, strong open-house traffic and even multiple offers at one point, the property is back on the market. Rather than simply reducing the price again, the seller is exploring another way to give qualified buyers a reason to take action.
The strategy puts the focus on a number buyers may care about even more than the list price: what they would actually pay each month.
A Different Kind of Seller Incentive
A seller-paid 2-1 buydown is a temporary financing arrangement designed to reduce the buyer’s mortgage payment during the first two years of the loan.
During the first year, the buyer’s payment is calculated using an interest rate that is 2 percentage points lower than the underlying rate. During the second year, the rate is 1 percentage point lower. Beginning in the third year, the temporary reduction ends and the payment returns to the amount based on the full loan terms.
The seller provides funds toward the cost of the temporary buydown, subject to the buyer’s loan program, lender requirements and the terms of the transaction.
For buyers who are comfortable with the long-term payment but would appreciate additional breathing room during the first couple of years, that temporary reduction can be meaningful.
It can also give sellers another way to make a property stand out in a market where buyers are paying close attention to affordability.
What That Could Mean for 12316 Coolmeadow Ln
At the current $525,000 asking price, several financing scenarios were calculated for the property. The examples show how the monthly-payment conversation can look different depending on the buyer’s loan type and down payment.
With a conventional loan and 5% down, the estimated payment is $3,887 per month during Year 1, $4,209 per month during Year 2 and $4,544 per month from Years 3 through 30.
The estimated seller cost for the buydown in this scenario is $11,920, or approximately 2.3% of the purchase price.
With a conventional loan and 10% down, the estimated payment is $3,713 per month during Year 1, $4,017 per month during Year 2 and $4,336 per month from Years 3 through 30.
The estimated seller cost in this scenario is $11,292, or approximately 2.2% of the purchase price.
For an FHA buyer putting 3.5% down, the estimated payment is $4,017 per month during Year 1, $4,343 per month during Year 2 and $4,685 per month from Years 3 through 30.
The estimated seller cost for this scenario is $12,124, or approximately 2.3% of the purchase price.
These figures include the principal, interest, property taxes and homeowners insurance assumptions provided for the financing scenarios.
Why Focus on the Payment Instead of Just the Price?
A price reduction is one way to attract buyers, but it isn’t the only option.
When a seller contributes toward a temporary buydown, the benefit is directed toward the buyer’s monthly payment during the first two years. That can create a different kind of incentive than simply lowering the purchase price.
For someone preparing to buy a home, the first few years can come with a long list of expenses. Moving costs, furniture, repairs, maintenance and other new-home expenses can add up quickly.
A lower initial mortgage payment may give a buyer more room in the budget while they settle into the property.
That doesn’t mean a 2-1 buydown makes a home universally more affordable. Buyers still need to qualify for the underlying mortgage and should be comfortable with the payment once the temporary buydown ends.
But for the right buyer, the timing of the savings can be just as important as the total amount.
Why the Strategy Could Matter for This Listing
Coolmeadow has already generated buyer interest.
The property has received more than 25 showings, strong open-house traffic and multiple offers at one point. The challenge now is not necessarily creating awareness of the home. It’s giving the next qualified buyer a compelling reason to take another look.
A seller-paid 2-1 buydown provides another way to approach that challenge.
Instead of making the entire conversation about whether $525,000 is the right price, the discussion can move toward how the purchase could be structured and what the monthly payment could look like under different financing scenarios.
That can be particularly useful for buyers who are watching their monthly budget closely.
It also gives real estate agents another talking point when they reach out to buyers who may have overlooked the property based on price alone.
The First Two Years Are Only Part of the Picture
One of the most important things buyers should understand about a 2-1 buydown is that the reduced payment is temporary.
The lower Year 1 and Year 2 payments do not continue for the entire mortgage term. Beginning in Year 3, the payment increases to the amount based on the underlying loan terms.
That means buyers should evaluate the home based on whether they can comfortably manage the long-term payment, not simply whether they can afford the introductory payment.
The actual payment will also depend on factors such as the buyer’s loan program, interest rate, credit profile, down payment, property taxes, homeowners insurance and other loan-specific costs.
For that reason, buyers should work directly with their lender to determine their actual qualification and payment.
Looking Beyond the List Price
The way buyers evaluate affordability has changed.
A home’s list price is still important, but it doesn’t tell the entire story. Two properties with similar prices can have very different monthly costs depending on taxes, insurance, financing terms, down payment and seller incentives.
That is why the conversation around Coolmeadow isn’t simply about a $525,000 purchase price.
It’s about understanding what that purchase could look like from a monthly-payment perspective.
For the right buyer, a seller-paid 2-1 buydown may provide temporary financial breathing room while still allowing the seller to maintain the home’s current positioning.
What Buyers and Agents Should Consider
A 2-1 buydown isn’t the right solution for every transaction. The buyer needs to qualify for the underlying loan, and the seller’s contribution must meet the requirements of the specific loan program and lender.
But it is another option worth discussing when a buyer likes the home but is concerned about the monthly payment.
For agents, it can also create a useful reason to reconnect with buyers who may have previously passed on the property.
Sometimes the difference between a buyer continuing to watch a listing and actually scheduling a showing isn’t another dramatic price reduction.
Sometimes it’s simply a different way of looking at the numbers.
Don’t Just Look at the Price. Look at the Payment.
12316 Coolmeadow Ln is currently offered at $525,000 in Dallas, and the seller-paid 2-1 buydown creates another opportunity to look at the property from a monthly-affordability perspective.
If you’re a buyer considering the home, or an agent working with someone who may be a good fit, talk with your lender about the available financing scenarios and whether a seller-paid 2-1 buydown could work for your situation.
The right home isn’t just about finding the right price. It’s also about finding a payment and financing structure that makes sense for your circumstances.
12316 Coolmeadow Ln, Dallas, TX | Offered at $525,000
Payment examples are estimates based on the financing scenarios provided for this property. Actual rates, payments, taxes, insurance, loan terms, qualification requirements and seller concessions will vary and should be confirmed with the buyer’s lender.

Leave a Reply